Lender field guide
Meet the QoE
A Field Guide to Quality of Earnings for SBA 7(a) Lenders. A practical guide to what a Quality of Earnings analysis should actually test, how it differs from a valuation, what SBA acquisition lenders should look for, and how to evaluate a provider.
10 pages · PDF · Updated Oct 2026 · No email required
What's inside
Ten pages on what good QoE work should test.
02
What changed in the latest update
SOP 50 10 8.1, Appendix 15 and the Sept 25, 2026 Technical Updates, side by side.
03
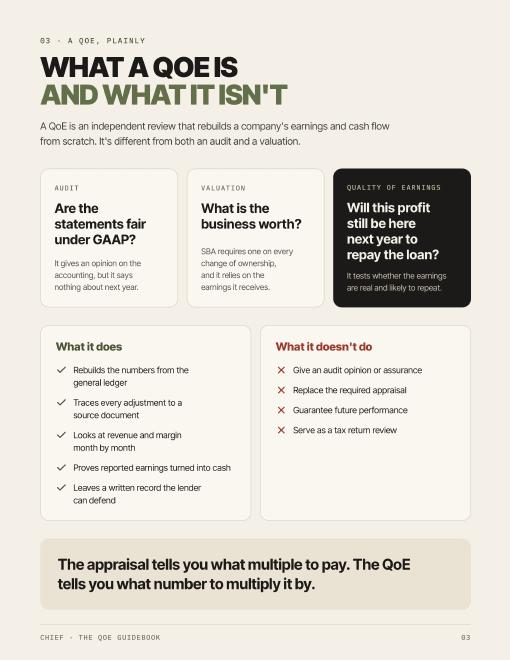
What a QoE is and what it isn't
How a QoE differs from an audit and from a valuation.
04
When the rules require one
A decision path for the $3M threshold and each ownership-change category.
05
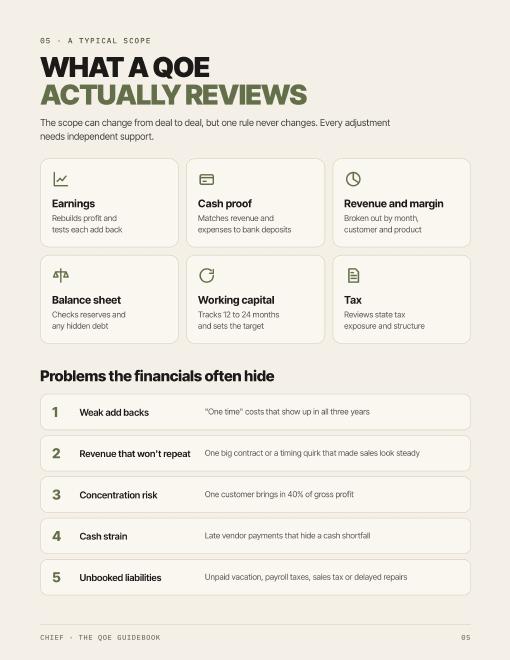
What a QoE actually examines
Earnings and add-backs, cash proof, revenue and margin, balance sheet, working capital, tax.
06
Proof of cash
How reported EBITDA is bridged to the cash the business actually produced.
07
Why the number matters
How supported EBITDA drives coverage, leverage and loan size.
08
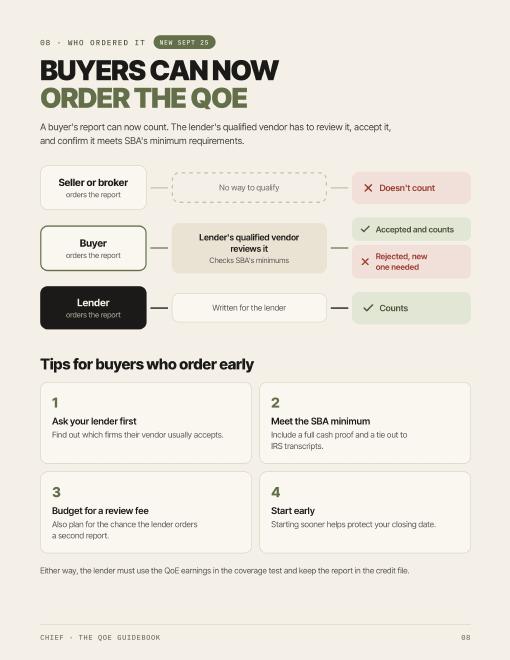
Buyer-ordered vs. lender-ordered work
When a buyer-ordered QoE can count for the lender.
09
Vetting a provider
Five questions to ask, plus red flags and signs of real diligence.
This summary is for informational purposes only. Lenders should rely on the applicable SBA SOP, notices, and their own legal and credit guidance for transaction-specific requirements.
What good QoE work looks like
A QoE should test the earnings, not repeat management's adjustments.
Illustrative example
From reported to normalized EBITDA
Reported EBITDA
$615K
Adjustments tested
+$245K
Supported
+$196K
Normalized EBITDA
$811K
Illustrative example
- Adjustment
- Owner compensation
- Management proposed
- $150K
- Chief supported
- $120K
- Evidence
- Payroll · General ledger · Tax return
- Conclusion
- Partially supported
Fictional figures for illustration. Not a Chief client report.
Why lenders share this
A common language for the deal team.
QoE can touch the BDO, underwriting, credit, valuation, and the borrower. The guide gives the team a practical framework for understanding what the analysis should test and what a lender should expect from the work.
Next step
Working on a live acquisition?
Need deeper financial due diligence? QoE + Detailed FDD, $15K. Discuss FDD
*Turnaround times assume all requested data is provided and Q&A is complete.